


Cost Per Cover: How to Amortise Buffet Equipment Properly
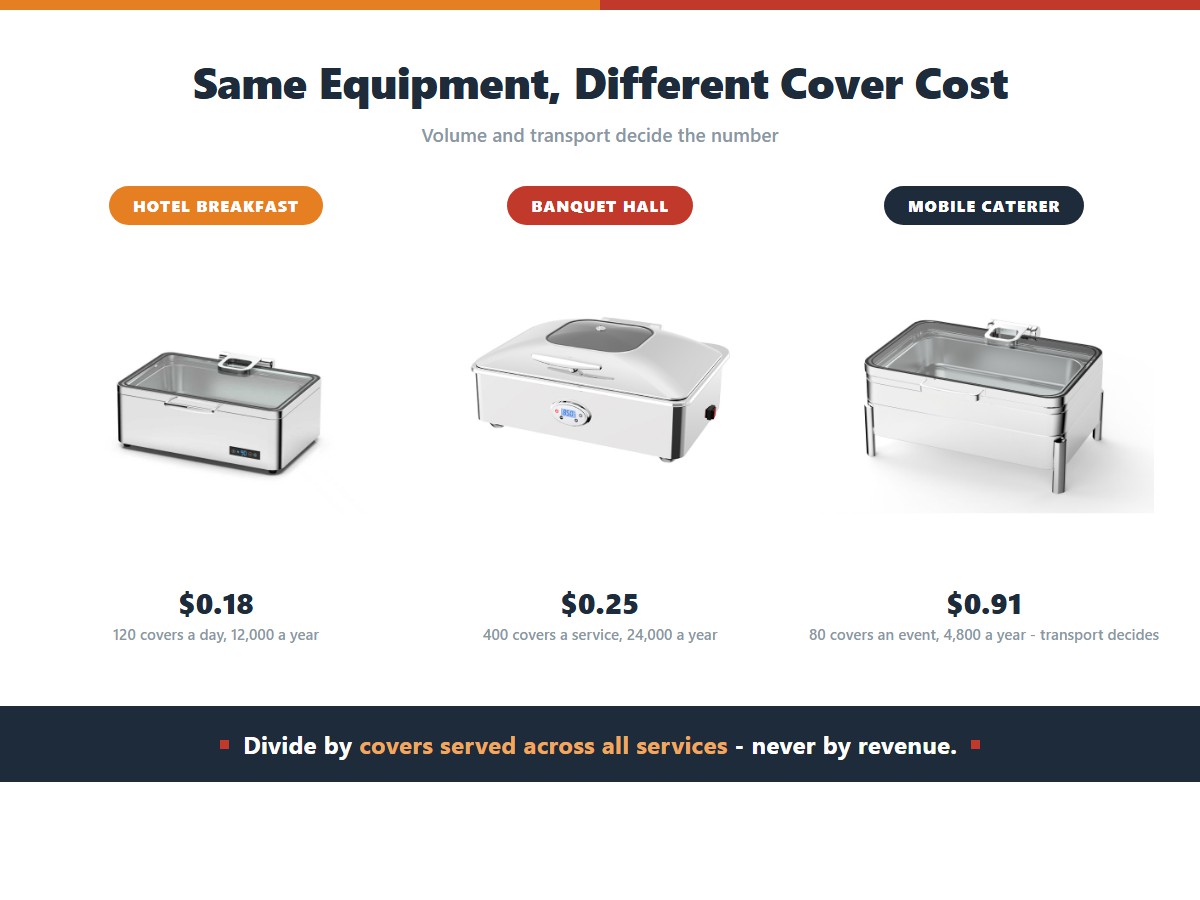
Short answer: divide the annualised cost of your buffet equipment by the number of covers you serve, and you get the true per-cover equipment cost. For a $6,000 line used over 5 years at 12,000 covers a year, that is about $0.10 per cover. Most operators get it wrong by using the purchase price instead of the annualised cost, and forgetting that the equipment serves a whole meal rather than one dish. See buffet station equipment; the numbers are below.
The formula, and the three ways people get it wrong
| Step | Calculation | Example | Common error |
|---|---|---|---|
| 1. Annualised capital cost | Purchase price ÷ useful life in years | $6,000 ÷ 5 = $1,200/yr | Using the full purchase price in year one |
| 2. Annual running cost | Fuel + electricity + maintenance | $900/yr | Forgetting the consumables |
| 3. Total annual cost | Step 1 + step 2 | $2,100/yr | Leaving out either half |
| 4. Covers per year | Covers served across all services | 12,000 | Counting only one service, or only the main one |
| 5. Cost per cover | Step 3 ÷ step 4 | $0.175 | Using covers at peak instead of across the year |
A worked example at three scales
The formula is simple, so the useful part is seeing how the answer changes with the size of the operation. These are typical figures for a stainless buffet line.
| Operation | Equipment | Covers/yr | Annual cost | Per cover |
|---|---|---|---|---|
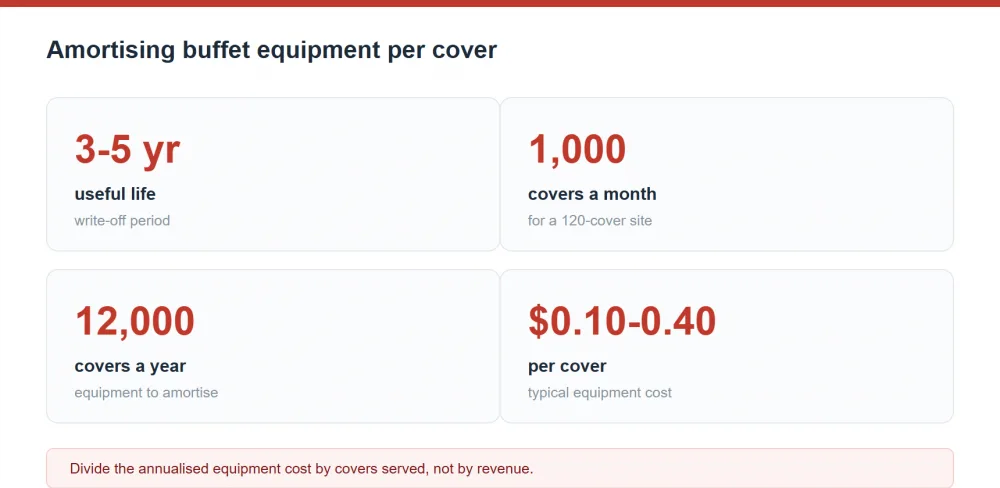
| Hotel breakfast, 120 covers | $6,000 over 5 yrs + $900 running | 12,000 | $2,100 | $0.18 |
| Banquet hall, 400 covers/service | $18,000 over 5 yrs + $2,400 running | 24,000 | $6,000 | $0.25 |
| Mobile caterer, 80 covers/event | $9,000 over 4 yrs + $2,100 running | 4,800 | $4,350 | $0.91 |
The pattern is the point. Cost per cover falls as the equipment is used harder. The hotel runs its line every day at 120 covers, so the capital is spread over 12,000 meals. The mobile caterer uses a larger kit 60 times a year, so the same per-unit capital lands on far fewer covers, and the running cost of transport, storage and setup dominates instead.
What to include and what to leave out
| Cost | Include? | Why |
|---|---|---|
| Equipment purchase | Yes, annualised | It is a real cost even though it is paid once |
| Fuel and electricity | Yes, per service | Roughly 40% of the running cost in most operations |
| Consumables: bulbs, gaskets, pans | Yes | Typically 5–10% of capital per year |
| Maintenance and repair | Yes | Budget 3–5% of capital per year |
| Cleaning labour | Yes, apportioned | Often the largest hidden cost after fuel |
| Transport, if mobile | Yes | Decisive for caterers; see Rental vs Buying |
| Storage space | Optionally, as a rent line | Real, but usually not in the food cost |
| Staff training | No, not for this figure | An overhead, not a per-cover equipment cost |
| Food cost and wages | No | These belong in the cost of the meal, not the equipment |
Where this calculation changes decisions
The number is worth computing because it changes three specific choices.
- Electric versus fuel. Electric units cost more to buy, and the per-cover figure is where that gap either closes or does not. An electric chafer that saves $0.05 per cover in fuel and $0.04 in labour over 12,000 covers has earned its $80 premium several times over. See Chafing Dish Total Cost of Ownership for the full five-year comparison.
- How much equipment to buy. If your per-cover cost is $0.18 and the food margin is $3.50, equipment is 5% of your economics and can be generous. If it is $0.91 for a mobile caterer with a $1.20 margin, equipment is nearly half your margin, and the cheaper kit becomes the rational choice.
- Whether to buy a bigger unit to reduce refills. A larger pan means fewer staff minutes on the line, and staff minutes are usually a bigger cost than the capital.
Common mistakes in the working
- Amortising over the wrong life. Stainless chafing dishes last 10–20 years, but the water pans, gaskets and fuel holders inside them do not. Amortise the consumable parts over 1–3 years and the chassis over 10–15, and the figure changes materially.
- Counting covers at peak. A 400-cover banquet hall might run 40 services a year at 300 covers, not 400. Overstating the denominator flatters the number.
- Forgetting that the same equipment serves every course. A chafing dish line serves breakfast, lunch and a dinner function in a hotel. It is not a per-meal cost if you charge it once per cover of the whole day.
- Ignoring the discarded food. Waste is not an equipment cost, but it is a per-cover cost and it belongs in the same discussion. See Buffet Food Waste Cost.
Spreadsheet structure that survives scrutiny
Keep one row per asset and one column per year, with the covers per year in a single cell above so every row divides by the same denominator. Include a utilisation column showing the percentage of services each unit actually worked, because a unit used 20% of the time is being amortised over far fewer covers than the headline number suggests. Review the sheet quarterly; the useful life assumption and the cover count both drift as the business changes, and a spreadsheet nobody revisits is a spreadsheet with fiction in it.
Frequently Asked Questions
Should equipment cost per cover be part of my food cost?
Not in the food cost itself, because it is not a food cost. It belongs in your full cost per cover, which is what you use to price a buffet or a banquet package. Keep the two separate in your accounts, but do use the combined figure when you set prices, because a buffet priced on food cost alone will lose money on the equipment.
What useful life should I use for a stainless chafing dish?
Ten to fifteen years for the frame and body of a good stainless unit, three to seven for 201-grade, and one to three years for the consumables: water pans, gaskets, fuel holders and light bulbs. A better approach than a single number is to keep a replacement schedule, because a unit that is going to need a new pan in year two changes its amortisation.
How do I allocate the cost when one line serves several revenue streams?
Allocate by usage, not by an arbitrary split. If the breakfast buffet does 12,000 covers a year and the lunch line does 3,000, weight the capital charge by that ratio. Where the same physical line is used across services, the simplest defensible method is to charge each service the full per-cover cost of the equipment it uses, which slightly over-recovers on a shared line but is far easier to explain than a weighted allocation.
Does a higher per-cover equipment cost make my buffet unprofitable?
Almost never, if you are in the normal range. Even at $0.90 per cover, equipment is a small share of the cost of a $12 buffet. The figure becomes decisive only in a low-margin operation, in a high-waste operation, or where a single equipment error, such as a line running on fuel in a site that could have gone electric, is out of proportion to the cover count.
Should I include the cost of the space the equipment occupies?
It is a real cost and it is worth tracking, but keep it in a separate line rather than folding it into the per-cover equipment figure. Space is a fixed overhead that exists whether or not the equipment is there, and mixing it into a variable cost per cover makes the number harder to use for pricing decisions.
How often should I recalculate this?
Quarterly is enough for a stable operation, and immediately after any change in covers, equipment or pricing. The inputs that drift are the cover count, the fuel and electricity price, and the replacement schedule. Annual recalculation is the most common, and it is a year of decisions taken on a number that has moved.
Related reading
- Corporate Event & Conference Catering Equipment Guide
- Buffet Equipment for Religious Events: Iftar to Christmas
- How to Choose a Beverage Dispenser for Cafés & Buffets
- Beverage Dispenser Cleaning & Sanitation Checklist
- Dishwasher or Hand Wash? What Actually Damages Your Buffet Equipment
- Buffet Warmers: Electric vs Fuel Cost per Cover